

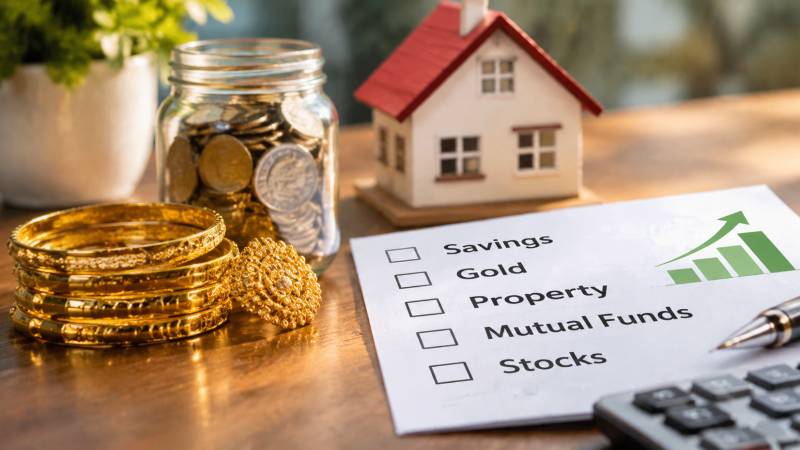
For a Pakistani family, saving money for the future can take years. A portion is set aside to purchase a plot of land, another is converted into gold, and some is deposited into a bank account. Some people regularly contribute to committees in the hope that, eventually, the accumulated sum will be enough to pay off a substantial debt. These practices are widespread across the country, particularly among households where years of sacrifice are required to gradually build financial security.
However, there is an interesting paradox in Pakistan's attitude towards money. Although people understand the importance of saving, a significant portion of their money is not channelled into recognised financial investment options. There are several reasons why Pakistanis do not invest, and, as a result, they often feel more comfortable putting their money into tangible assets rather than financial instruments that may offer different opportunities to accumulate wealth.
For many families, gold is more than simply jewellery; it is a well-established store of wealth and a representation of financial security. Similarly, property offers something tangible. A plot of land can be passed down through generations, visited and owned. Committees and other informal savings arrangements likewise rely heavily on personal relationships and familiarity. In contrast, a mutual fund or an investment in listed securities may seem distant, complex and difficult to evaluate.
This raises an important question: why are some Pakistanis willing to take financial risks to preserve their money but reluctant to invest it through formal channels? There are not enough reliable connections between household savings and established investment avenues. Consider someone who has accumulated a small amount of money after saving for a few months. They may participate in a committee, maintain a bank account or purchase gold. However, the prospect of making a financial investment presents a different set of challenges. Which mutual fund should they choose? How do government-issued securities work? What would happen if the market declined? How much money should they invest, and for how long?
For someone without prior exposure to financial markets, these questions can become barriers before the investment process even begins. Additionally, there is a persistent belief that investing in the stock market amounts to little more than speculation. This view is reinforced by stories of financial losses, market volatility and occasional experiences of poorly informed investment decisions. When a novice investor sees the value of their portfolio decline, they may conclude that the market is inherently dangerous.
However, speculation and investing are not the same thing. Investing involves allocating capital while considering risk, projected returns and the investment horizon. Speculation involves a different set of considerations, particularly when it is driven by short-term price movements without sufficient analysis. Treating every market participant as a trader discourages people from exploring investment opportunities that might suit their financial circumstances. This is why the distinction matters.
Not every saver in Pakistan needs to become a stock market trader. It requires a financial system that enables regular people to make well-informed choices about the use of their money, the risks they take, and the opportunities they seize.
Financial literacy can therefore contribute to the solution, but it cannot provide a complete explanation. People must understand risk and return, inflation, diversification and the differences between various financial instruments. More importantly, they must recognise that an investment that works for one person may not be suitable for another. However, awareness alone cannot overcome every hurdle. Long-term investments cannot be expected to take priority in a household struggling with financial difficulties. Similarly, even financially literate individuals may be reluctant to invest if they do not trust the institutions and intermediaries handling their money.
Trust is particularly important when making financial decisions. Individuals are unlikely to invest their hard-earned savings in products or organisations with which they are unfamiliar. Opening an investment account, choosing a broker, completing paperwork, understanding fees and selecting the right product may seem far more complicated to many novice investors than simply maintaining a traditional bank account. Regulators and the financial sector have a significant responsibility in this regard. Improving trading infrastructure and launching new products are not enough to make financial markets more accessible. This requires simpler onboarding processes, transparent fees, effective investor protection and easily understandable information.
Domestic savings can boost economic activity, finance business expansion and generate employment when they are channelled efficiently into productive investments. In particular, capital markets can offer businesses alternatives to conventional bank borrowing. A larger investor base can also contribute to the development of deeper and more vibrant financial markets. On the other hand, an opportunity is wasted if household savings continue to be concentrated in a limited number of assets or remain outside formal financial channels. While corporations face a more constrained pool of domestic long-term capital, individuals may miss suitable opportunities to diversify their wealth.
This does not mean that bank accounts, gold or real estate have no place in household financial planning. Each serves a distinct purpose, and people's investment horizons, risk tolerances and financial responsibilities vary. The challenge is to develop a framework that makes formal financial investments a legitimate, accessible and understandable component of broader financial planning. Not every saver in Pakistan needs to become a stock market trader. What is needed is a financial system that enables ordinary people to make well-informed decisions about how they use their money, the risks they take and the opportunities they pursue. The real challenge is not teaching Pakistanis how to save. It is giving their savings somewhere productive to go.